
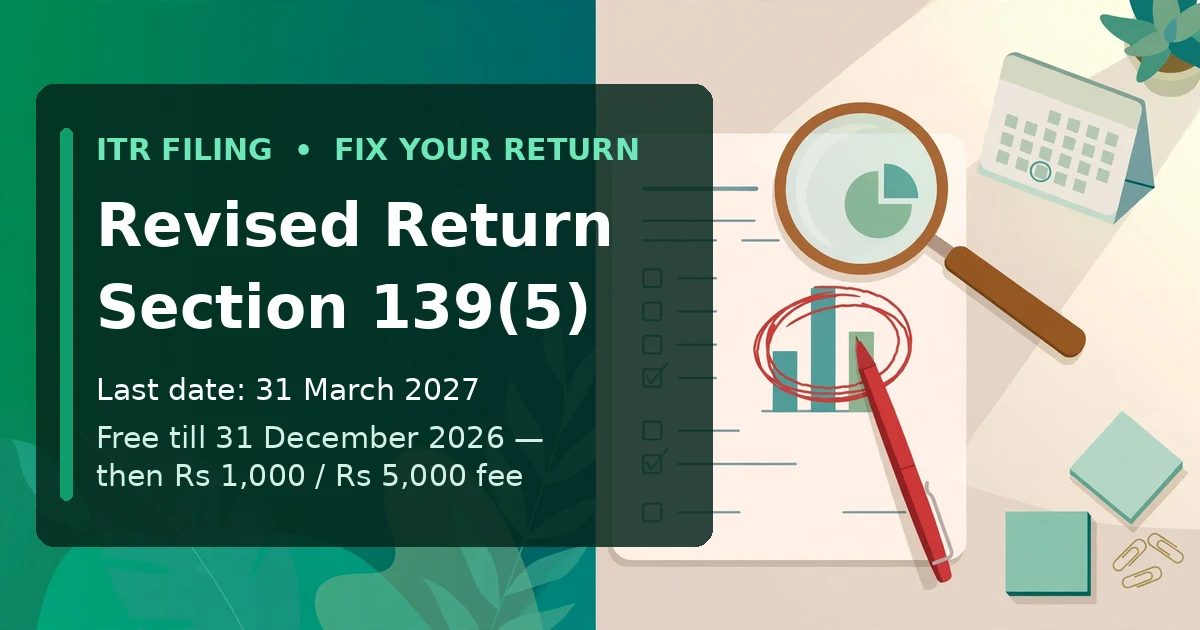
You filed your income tax return, and then you spotted a mistake. Maybe you missed some FD interest. Maybe you claimed a deduction you were not eligible for. Or you picked the wrong ITR form. A revised return lets you fix it — but only till a fixed last date, and from January 2027 it comes with a fee.
A revised return is a corrected version of an ITR you have already filed, filed under Section 139(5) of the Income-tax Act, 1961. For Assessment Year 2026-27, you can file it till 31 March 2027, or before your assessment is completed, whichever is earlier. It is free if you file by 31 December 2026; after that, a fee of Rs 1,000 or Rs 5,000 applies under the new Section 234-I.
What is a revised return?
A revised return is filed under Section 139(5) of the Income-tax Act, 1961. It is meant for taxpayers who have already submitted a return but later find an error or an omission in it.
The revised return replaces the original one completely. The department treats the revised return as the return for that year, and the original one stops counting. You must file the whole corrected return, not just the one line you want to change. That is the most common misunderstanding — people think they can send only the correction. You cannot.
Common reasons people file a revised return:
- Missed income — interest from a fixed deposit or savings account that was not shown.
- Wrong deduction — a Section 80C or 80D deduction claimed by mistake, or a valid deduction left out.
- Wrong ITR form — you used ITR-1 but your income needed ITR-2.
- Wrong bank details — the account number or IFSC code entered for the refund was incorrect.
- Missed TDS credit — tax deducted at source, shown in Form 26AS, was not claimed.
- Wrong regime — you picked the old regime but the new regime would have saved more tax, or the other way round.
If you never filed a return at all, you cannot use a revised return. In that case you must file a belated return under Section 139(4) instead. The two are different, and the comparison table later in this article shows how.
What changed in 2026: a longer window, but a new fee
For AY 2026-27, the rules for revised returns changed. The Finance Act, 2026 amended Section 139(5) and added a new fee section, Section 234-I. Two things changed:
- The window got longer. Earlier, a revised return had to be filed by 31 December of the assessment year. Now you get three extra months — till 31 March 2027.
- The extra months are not free. Revisions filed between 1 January 2027 and 31 March 2027 attract a fee under Section 234-I.
The Income-tax Act, 2025, which applies from tax year 2026-27 onwards, carries the same structure under new numbers. Returns for AY 2026-27 (income of FY 2025-26) are still filed under the 1961 Act, so Section 139(5) is the number that matters for you right now.
| Provision | Income-tax Act, 1961 | Income-tax Act, 2025 |
|---|---|---|
| Return of income | Section 139 | Section 263 |
| Belated return | Section 139(4) | Section 263(4) |
| Revised return | Section 139(5) | Section 263(5) |
| Updated return (ITR-U) | Section 139(8A) | Section 263(6) |
| Late filing fee | Section 234F | Section 428 |
What is the last date to file a revised return for AY 2026-27?
The deadline is 31 March 2027, or before the completion of your assessment, whichever is earlier. If the department completes your assessment first, the window closes even if 31 March has not passed.
The fee-free window is shorter than the deadline. File by 31 December 2026 and there is no fee at all. File between 1 January 2027 and 31 March 2027 and the Section 234-I fee applies:
| Filing period | Total income up to Rs 5,00,000 | Total income above Rs 5,00,000 |
|---|---|---|
| On or before 31 December 2026 | Nil | Nil |
| 1 January 2027 to 31 March 2027 | Rs 1,000 | Rs 5,000 |
The practical advice is simple: do not wait for March. The December deadline is the one that costs nothing, and it is also the last date for a belated return. If you know there is a mistake in your return, fix it before 31 December 2026.
How much does a revised return cost?
A revised return has two possible costs: the fee, and interest on any tax that was left unpaid.
- Fee — nil till 31 December 2026; Rs 1,000 or Rs 5,000 under Section 234-I after that, as per the table above.
- Interest — if the correction means more tax was due, interest under Section 234A is charged at 1% per month on the unpaid tax, counted from the original due date (31 July 2026 for most salaried taxpayers) till the date you pay.
Worked example 1: missed income means extra tax
Ramesh, a salaried employee with a total income of Rs 14,00,000, filed his original ITR on 15 July 2026. He later noticed that Rs 50,000 of interest from a fixed deposit was missing from his return.
- Tax on the missed interest at his 20% slab: 20% of Rs 50,000 = Rs 10,000
- Health and education cess at 4% of the tax: 4% of Rs 10,000 = Rs 400
- Total extra tax = Rs 10,400
If Ramesh files the revised return before 31 December 2026, he pays only the Rs 10,400 — no fee. If he files it in February 2027, he also pays a fee of Rs 5,000 (his total income is above Rs 5 lakh), plus interest under Section 234A at 1% per month on the Rs 10,400 from August 2026 till the month he pays. Waiting costs him roughly Rs 5,700 extra for the same correction.
Worked example 2: a missed deduction means a bigger refund
Priya, also in the 20% slab, filed her return on time but forgot to claim Rs 50,000 of PPF contribution under Section 80C. Her revised return claims it.
- Tax saved: 20% of Rs 50,000 = Rs 10,000, plus 4% cess = Rs 10,400
- Her refund goes up by Rs 10,400.
A revised return can increase your refund. It is not only for paying extra tax. If you left out a deduction, revising is how you get the money back.
How to file a revised return online — step by step
You file a revised return on the Income Tax e-filing portal, incometax.gov.in. The steps are:
- Log in to incometax.gov.in with your PAN, password and OTP.
- Click e-File, then Income Tax Returns, then File Income Tax Return.
- Select Assessment Year 2026-27. Do not pick Tax Year 2026-27 — that is a different year under the new Act.
- In the filing type, select Revised Return under Section 139(5).
- Enter the acknowledgement number and date of filing of the original return. You will find both in the ITR-V acknowledgement of your first filing. If you have revised before, use the acknowledgement number of the latest return.
- Choose the ITR form. Keep the same form unless the original choice was wrong — a wrong form is itself a valid reason to revise.
- Correct the figures: income, deductions, bank details, TDS credit, or whatever was wrong. File the full return with all schedules, not only the changed part.
- Click Compute Tax and check the result — extra tax payable, or a higher refund.
- Pay any extra tax as self-assessment tax through net-banking, UPI or debit card, and enter the challan details in the return.
- Submit the return. The portal will generate a new acknowledgement number.
E-verify within 30 days. Verify the revised return using Aadhaar OTP, net-banking, or by sending the signed ITR-V to the CPC in Bengaluru. If you do not e-verify, the revised return is treated as invalid and the original return stays on record. The correction simply does not count.
After filing, check the status under e-File > Income Tax Returns > View Filed Returns. The revised return shows as a separate entry with its own acknowledgement number. If a refund was already issued on the original return, the department adjusts it against the revised figures.
Revised return vs belated return vs updated return (ITR-U)
These three are often confused. They fix different problems, and picking the wrong one wastes time.
| Feature | Revised Return (Section 139(5)) | Belated Return (Section 139(4)) | Updated Return — ITR-U (Section 139(8A)) |
|---|---|---|---|
| Who can file | Anyone who has already filed a return | Taxpayers who never filed at all | Anyone, whether or not a return was filed earlier |
| Last date for AY 2026-27 | 31 March 2027, or before assessment is completed | 31 December 2026 | Up to 48 months after the end of the assessment year — 31 March 2031 |
| Fee or cost | Nil till 31 December 2026; Rs 1,000 or Rs 5,000 under Section 234-I after that | Late fee under Section 234F: Rs 1,000 (income up to Rs 5 lakh) or Rs 5,000 (above Rs 5 lakh), plus interest under Section 234A at 1% per month | Additional tax of 25% if filed by 31 March 2028, 50% by 31 March 2029, 60% by 31 March 2030, and 70% by 31 March 2031 |
| What it can do | Correct any mistake, change figures, switch ITR form, update bank details | File a return for the first time; a belated return can itself be revised later | Add income that was missed earlier, after all other windows have closed |
| What it cannot do | Cannot be filed if no return was filed at all; cannot be filed after assessment is completed | Cannot carry forward business or capital losses (house property loss is allowed); the old regime option is not available | Cannot report a loss, cannot reduce tax liability, cannot increase a refund |
The order matters: revise first if you can, because it is free till December. A belated return is the fallback if you never filed. ITR-U is the last resort — it exists for income you missed entirely, and it always costs extra tax.
What you can and cannot change in a revised return
You can change:
- Income from salary, house property, capital gains and other sources.
- Deductions under Chapter VI-A, such as Section 80C and Section 80D.
- The ITR form, if you selected the wrong one the first time.
- Bank account number, IFSC code and other refund details.
- The tax regime in most cases, if the original return was filed on time. If the original return was belated, the old regime may not be available when you revise it.
You cannot:
- File a revised return if you never filed any return for the year — that needs a belated return.
- File a revised return after the assessment for that year is completed.
- Change the assessment year — a revised return always belongs to the same year as the original.
- Use a revised return to carry forward a loss that a belated return could not carry forward.
5 mistakes to avoid
- Filing after the assessment is completed. Once the assessment order is passed, the revision window is closed. Check your assessment status before you start.
- Forgetting to e-verify. An unverified revised return is invalid. The original return stays effective, and your correction is ignored. Verify within 30 days of filing.
- Using a revised return when nothing was filed. If you never filed for AY 2026-27, the correct route is a belated return under Section 139(4), open till 31 December 2026.
- Correcting only the wrong figure. A revised return must contain the complete, corrected ITR — every schedule, every figure. The portal replaces the original return in full.
- Ignoring mismatches in AIS and TIS. Before revising, cross-check your figures with Form 16, the Annual Information Statement (AIS), the Taxpayer Information Summary (TIS) and Form 26AS. A revision that still disagrees with AIS is likely to draw a notice. Our guide on Form 26AS vs AIS vs TIS explains how to spot the mismatch first.
Frequently asked questions
What is the last date to file a revised ITR for AY 2026-27?
The deadline is 31 March 2027, or before the completion of your assessment, whichever is earlier. Filing by 31 December 2026 is free; revisions between 1 January and 31 March 2027 attract a fee of Rs 1,000 or Rs 5,000 under Section 234-I.
Is there a fee for filing a revised return?
No fee if you file on or before 31 December 2026. Between 1 January 2027 and 31 March 2027, the fee is Rs 1,000 if your total income is up to Rs 5 lakh, and Rs 5,000 if it is above Rs 5 lakh. Interest under Section 234A at 1% per month applies separately if any tax was left unpaid.
How many times can I revise my ITR?
You can file a revised return any number of times before the deadline. There is no limit. Each new revision replaces the previous one, and you must quote the acknowledgement number of the latest return.
Can I file a revised return if I never filed an ITR?
No. A revised return needs an original return to correct. If you have not filed anything for AY 2026-27, file a belated return under Section 139(4) by 31 December 2026 instead. Our belated ITR guide covers the fee and the steps.
What is the difference between a revised return and a belated return?
A revised return corrects a return that was already filed. A belated return is the first return filed after the original due date, by someone who did not file at all. A revised return is free till 31 December 2026; a belated return always carries a late fee under Section 234F plus interest.
Can I change the ITR form in a revised return?
Yes. If you picked the wrong ITR form the first time, you can select the correct form while filing the revised return. Our ITR form guide explains which form fits which income.
What happens if I do not e-verify my revised return?
The revised return is treated as invalid. The original return stays on record and your corrections are ignored. E-verify within 30 days of filing, using Aadhaar OTP, net-banking, or by sending the ITR-V to the CPC.
Can I revise a belated return?
Yes. A belated return can be revised up to 31 March 2027, and the same fee rules apply — free till 31 December 2026, then Rs 1,000 or Rs 5,000 under Section 234-I. One restriction: when you revise a belated return, the old tax regime may not be available.
Official sources
- incometax.gov.in — the e-filing portal: file the revised return, check its status and e-verify. (incometax.gov.in)
- incometaxindia.gov.in — the department’s information portal for the Income-tax Act, forms and circulars. (incometaxindia.gov.in)
- CBDT / Finance Act, 2026 — the amendment to Section 139(5) and the new Section 234-I fee, plus the 1% per month interest rule under Section 234A. For the interest rules in detail, see our guide on interest under Sections 234A, 234B and 234C.
Reviewed by Asuthod Rathod, CA
Last updated: 7 November 2026
This article provides general information only. It does not constitute professional tax advice. Tax rules change often — verify the current position on the official portal or consult a qualified tax professional before filing.
Editorial byline for eircicai freelancer tax and ITR filing guides — covering 44ADA presumptive tax, advance tax, and ITR filing. Content is reviewed by Asuthod Rathod, CA.